
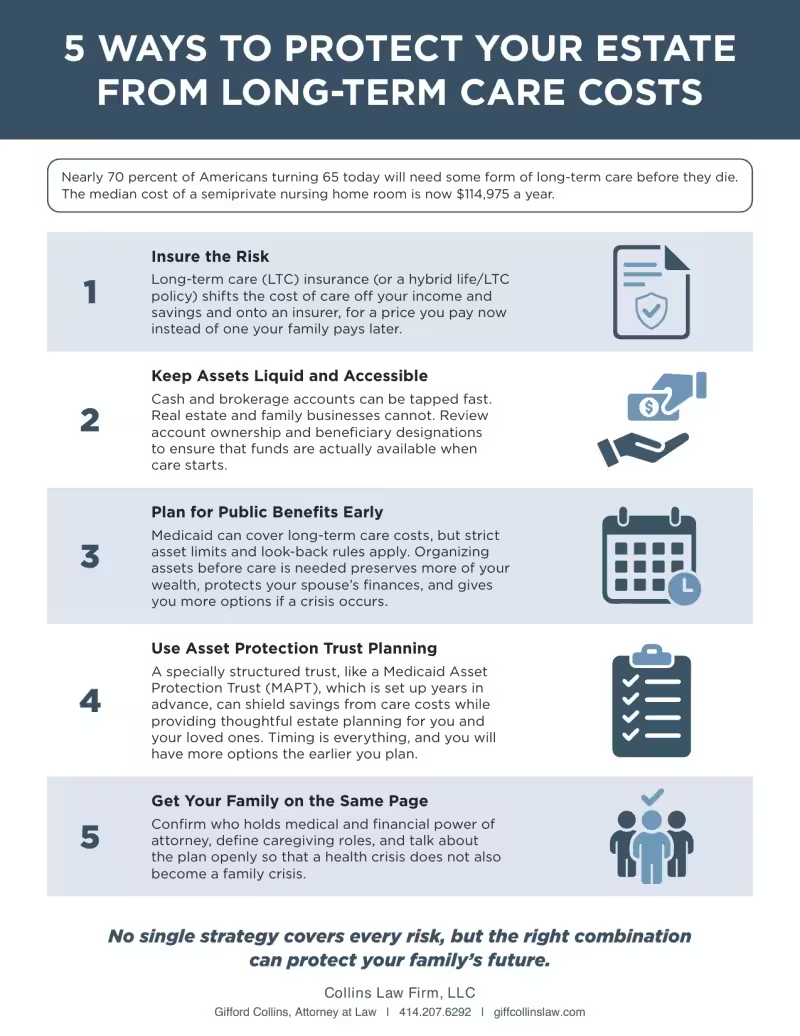
Nearly 70 percent of Americans turning 65 today will need some form of long-term care. Most estate plans are not built for what it costs.
The median cost of a semiprivate nursing home room is now $114,975 a year, nationally. That bill does not wait for a plan to catch up, and it is paid out of exactly the assets most families intended to pass on.
The good news is that this is one of the more solvable problems in estate planning, as long as the work happens before care is needed rather than during a crisis. This guide covers five strategies and what each one actually requires.
What’s inside:
- Insuring the risk, and how a long-term care or hybrid policy shifts the cost off your savings
- Keeping assets liquid, so funds are actually available when care starts
- Planning for public benefits early, including the asset limits and look-back rules that catch families off guard
- Asset protection trust planning, and why the timing matters more than the structure
- Getting your family aligned on powers of attorney and caregiving roles before a health crisis forces it
We will email the guide to the address you provide. We do not sell or share your information. Submitting this form does not create an attorney client relationship.